
Life Insurance
Secure your family's financial future. Affordable protection that pays out when it matters most.
Your mortgage is likely your largest financial commitment. A decreasing term policy mirrors your outstanding balance: if you die before it's repaid, your family won't have to sell the family home to cover the debt.
If your income disappears overnight, how would your family maintain their standard of living? A lump sum or family income benefit policy replaces lost earnings so your partner and children can continue with minimal disruption.
Estates above the nil-rate band (currently £325,000, or up to £500,000 with the residence nil-rate band) are subject to 40% IHT. A whole-of-life policy written in trust can provide a lump sum to cover the tax bill: meaning your beneficiaries inherit what you intended, not what's left after HMRC.
The average UK funeral now costs over £4,000. A modest whole-of-life or over-50s plan ensures your family can give you the send-off you'd want without financial stress at an already difficult time.
Business owners and partners can use life insurance to fund a buy-sell agreement: enabling surviving partners to purchase the deceased's share without forcing a fire sale of assets or taking on crippling debt.
Personal loans, credit card balances, and car finance don't disappear on death: they become a liability for your estate. Life insurance ensures these are cleared so your family inherits assets, not obligations.
Level Term Insurance
Fixed payment, fixed death benefit over 10-40 years
Decreasing Term
Benefit reduces over time (ideal for mortgages)
Family Income Benefit
Monthly income for your family instead of lump sum
Whole of Life
Coverage that never expires, guaranteed payout
Waiver of Premium
Premiums waived if you become unable to work
Family Coverage
Protect multiple family members in one policy
Life insurance comes in a handful of shapes, and the difference between them matters more than the difference between insurers. Each of these explains what the shape does, who it suits and where it falls short.
Term Life Insurance: Cover for a fixed number of years: the starting point for most families.
Level Term: A fixed payout that does not change across the term.
Decreasing Term: Falls alongside a repayment mortgage, and costs the least.
Increasing Term: Rises each year so inflation does not erode the cover.
Mortgage Life Insurance: Sized to your mortgage, whether repayment or interest-only.
Joint Life Insurance: One policy for two people, and when two singles are better.
Whole of Life: No end date, used mainly to fund an inheritance tax bill.
Over 50s Life Insurance: Guaranteed acceptance with no medical questions.
Protect your loved ones: Ensure your family can pay the mortgage, cover living costs, and maintain their lifestyle.
Affordable premiums: Life insurance is surprisingly inexpensive. A 35-year-old non-smoker can get £250,000 cover for as little as £15/month.
Tax-free payout: Life insurance benefits are paid tax-free to your beneficiaries.
Final wishes: Cover funeral costs and outstanding debts so your family isn't burdened.
The following are illustrative examples only. They do not represent real clients or actual cases. Individual policy terms, eligibility and outcomes will vary.
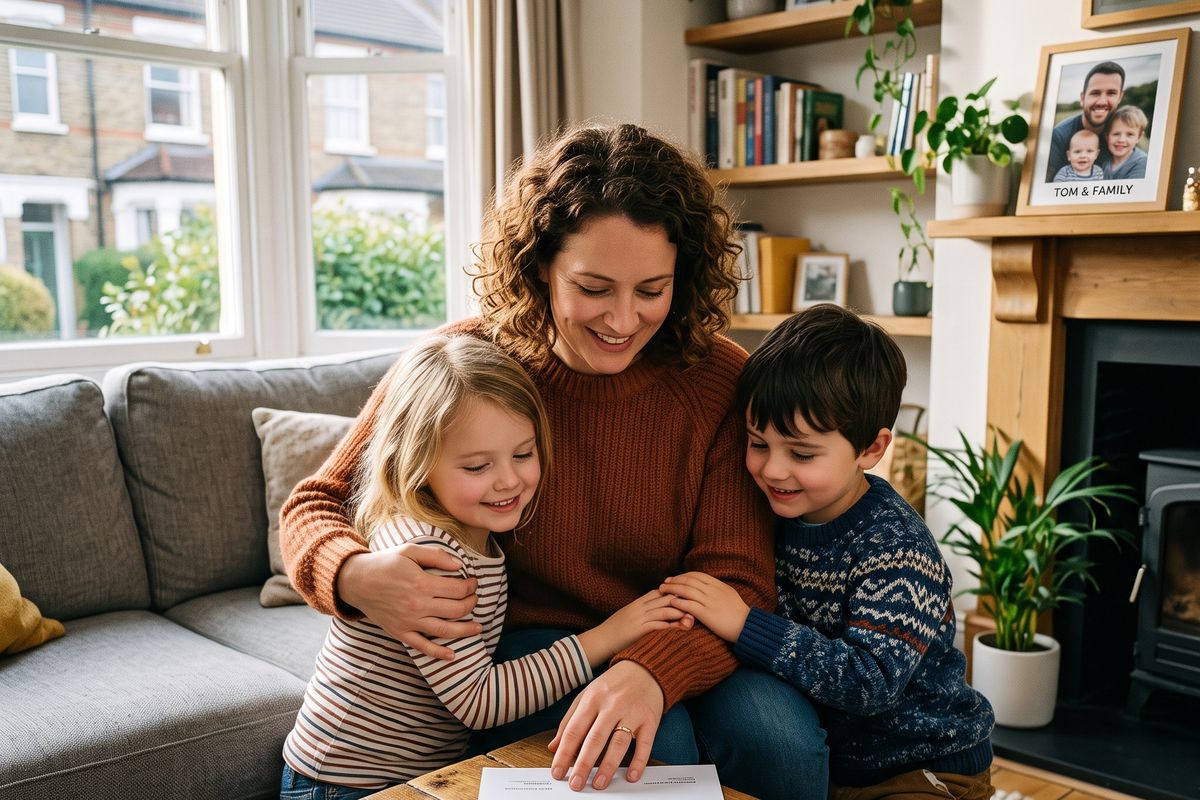
Tom and Jess took out joint life insurance when they bought their first home aged 31. Three years later, Tom was killed in a road accident. The decreasing term policy cleared their £220,000 mortgage in full. A separate family income benefit policy then paid Jess £1,800/month for 20 years: allowing her to stay in the family home and maintain stability for their two young children.
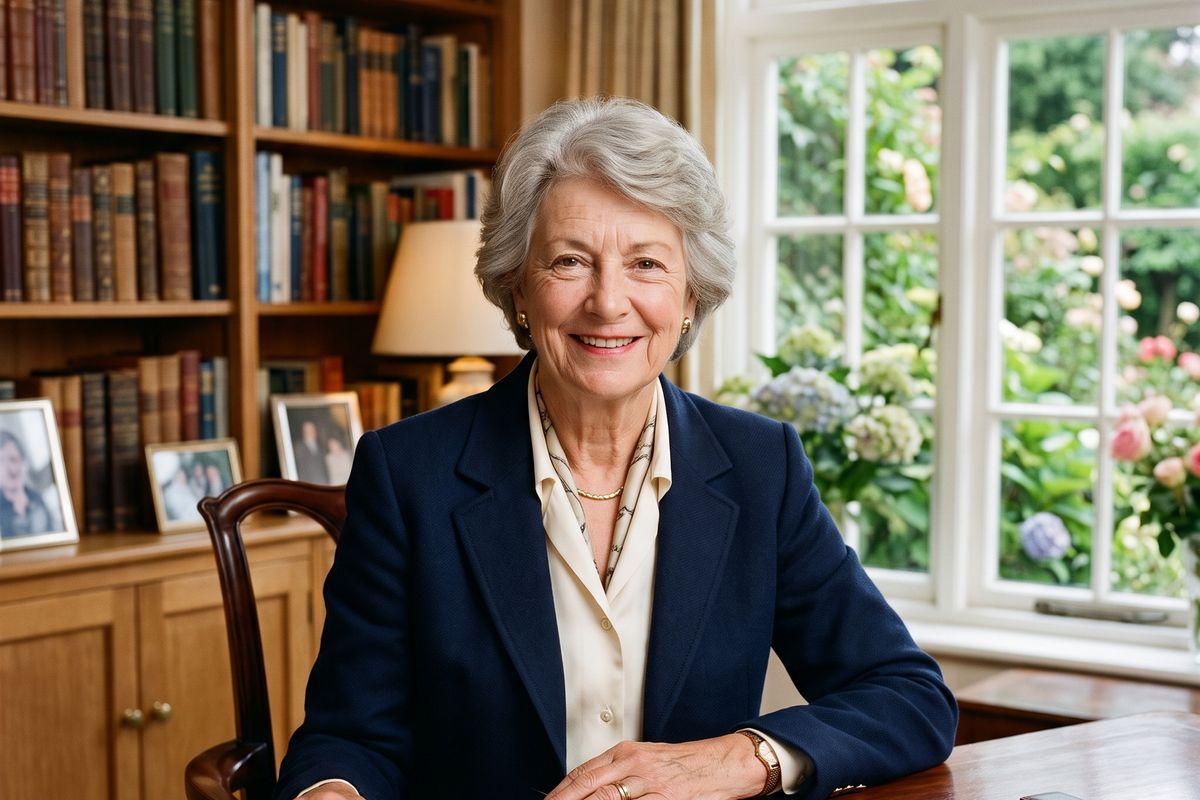
Margaret, 68, had an estate valued at £900,000: well above the nil-rate band. Her financial adviser calculated a potential IHT liability of over £200,000. A whole-of-life policy written in trust was arranged for exactly this amount; the premium was paid from income and the payout, falling outside the estate, was available within days for the beneficiaries to settle the tax bill.
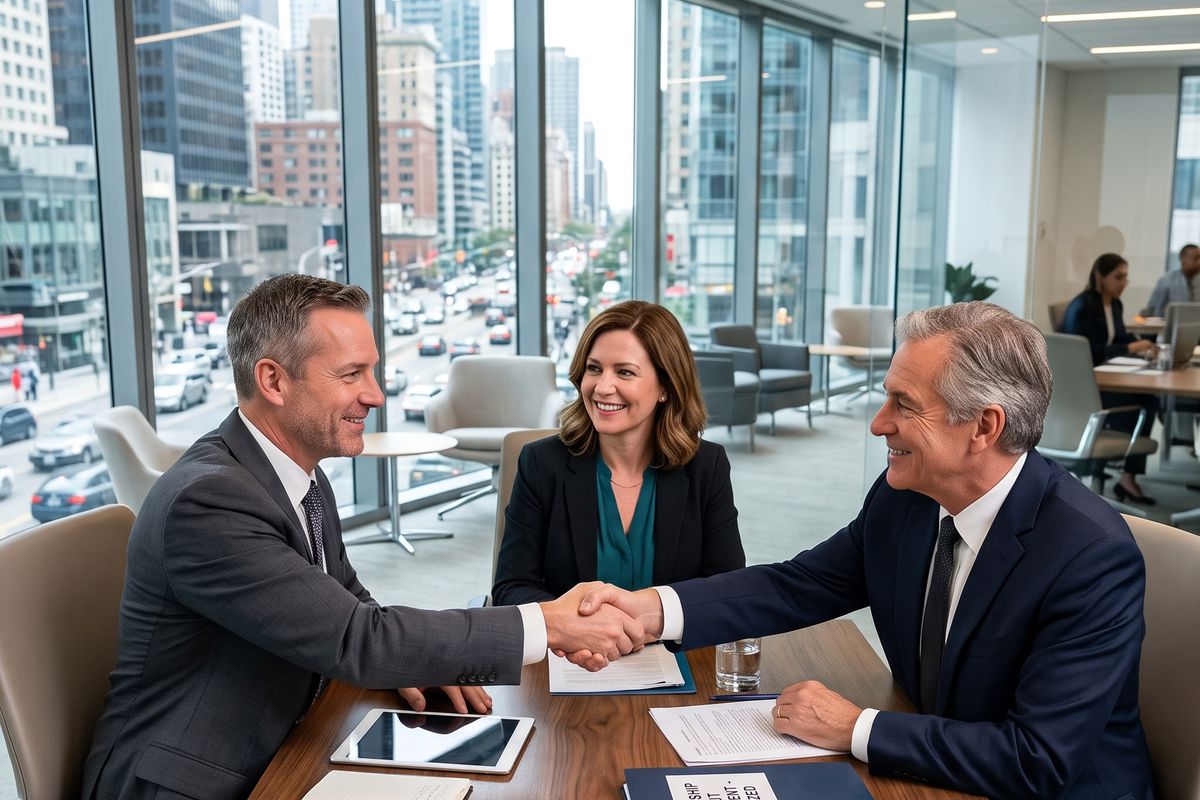
Two business partners each took out cross-option life insurance policies. When one partner died unexpectedly, the surviving partner received the insurance proceeds and used them to buy the deceased's share from the estate: ensuring the business continued, the deceased's family received fair value, and no fire sale of assets was necessary.
A common starting point is 10x your annual income: though the right amount depends on your outstanding debts, your dependants' needs, and how long you'd want income replaced. Baker Hudson Health will guide you through a proper needs analysis before comparing quotes.
For mortgage protection, the cover should at minimum match your outstanding balance. For family income protection, consider how much your partner would need per month and for how many years. For IHT planning, the calculation is based on your estimated estate value and applicable nil-rate bands.
Your circumstances
Rough figures are fine. You can refine everything with an adviser later.
How long would your family need your income replaced for? Many people choose until their youngest child is financially independent.
We'll assume roughly £25,000 towards education & childcare costs per child. Adjust below if needed.
Include any death-in-service or existing personal policies. This reduces what you need to add.
Your estimated cover
Based on the DIME method
No obligation. An adviser will talk through the right level and type of cover for you.
This is a guide only, not financial advice, and doesn't replace a full review with an adviser.
Life insurance is often surprisingly affordable. Some examples of what healthy non-smokers can typically expect:
Age 30, £250,000 level term, 25 years: from approximately £12–18/month
Age 40, £200,000 level term, 20 years: from approximately £20–30/month
Age 50, £150,000 level term, 15 years: from approximately £40–60/month
Smokers, those with existing health conditions, or higher-risk occupations will pay more, and some may need specialist underwriting. Baker Hudson Health has access to the full market including specialist medical underwriters: and we will help manage any underwriting disclosures to get you the best possible terms.
Independent & Regulated
FCA authorised. We work for you, not the insurers: impartial advice with no exceptions.
We Explain the Small Print
No hidden clauses, no jargon. We walk you through your policy in plain English until every question is answered.
Built on Trust & Honesty
Baker Hudson Health was founded on solid relationships. We do all the work on your behalf: your interests always come first.
Protect Your Family Today
Get a free, no-obligation quote in minutes.

Your Future Protected
Expert insurance advice for those who demand the best. Tailored protection for your life and business.
Understand Your Needs
We take time to understand exactly what you need and why.
Find the Best Options
We search the market to find premium solutions tailored to you.
Complete Support
We manage everything from setup through to claims support.
Independent & Regulated
FCA authorised. We work for you, not the insurers.
Expert Advisers
Decades of experience across all protection products.
Significant Savings
Our clients typically save 30% on their renewal when switching.
Ready for Expert Protection?
Let's find the right coverage for your life and business. No pressure, no commitment.
Cirencester Road, Stroud
GL6 8PE